August 31, 2026 • By Jeff Gaudette
The Three-Legged Retirement Stool Lost a Leg. Here’s How Today’s Retirees Can Rebuild It.
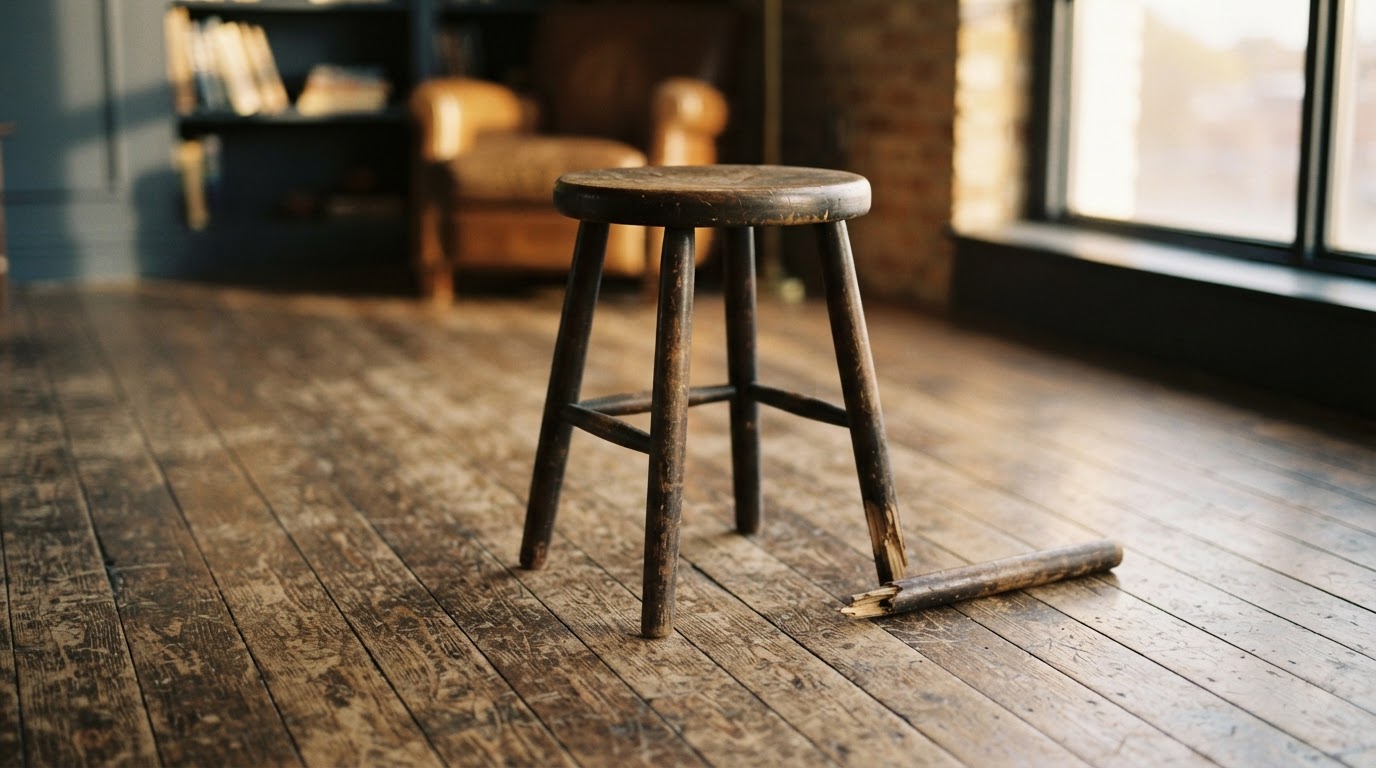
For decades, retirement planning was often described as a three-legged stool.
The three legs were simple: A pension. Social Security. Personal savings.
Each served a different purpose, and together they created something many retirees today are finding increasingly difficult to achieve: predictable income that could last for the rest of their lives.
But over the past several decades, one of those legs has largely disappeared for millions of American workers.
The traditional pension has been replaced by the 401(k), 403(b), 457 plan and other defined-contribution retirement accounts.
That change fundamentally altered retirement in America.
Your Parents Retired With a Paycheck. You May Be Retiring With an Account Balance.
For many members of previous generations, retirement didn’t necessarily begin with a large investment account and the question:
“How much of this can I safely spend?”
Instead, they may have retired with several sources of predictable monthly income. Social Security arrived every month. A pension arrived every month. Savings supplemented those checks when necessary.
The retiree didn’t have to decide how much of the pension to withdraw. They didn’t have to worry about selling investments during a market downturn to produce that month’s pension payment.
The pension was designed to do something very specific: Turn years of work into a stream of retirement income.
Today, many workers have been given something very different. They have been given a pile of money.
From Defined Benefit to Defined Contribution
Traditional pensions are known as defined-benefit plans. The employer generally assumes the responsibility for funding the plan and providing the promised retirement benefit.
The 401(k) changed that equation.
A 401(k), 403(b) or 457 plan is generally a defined-contribution plan. Instead of your employer promising you a particular retirement paycheck, money is accumulated in an account for you.
That shift transferred several important responsibilities to the employee. You now have to determine how much to save, how to invest it, how much you can withdraw in retirement, how market losses could affect your income and, perhaps most importantly:
“How do you make sure the money lasts as long as you do?”
That’s a very different retirement problem.
We Got Better at Accumulating Money — But Not Necessarily at Turning It Into Income
The retirement industry spent decades teaching people how to accumulate money: contribute to your 401(k), get the company match, increase your contribution, diversify and invest for growth.
Those are important lessons. But somewhere around retirement, the objective changes.
You’re no longer simply asking, “How large can I make my account?” Now you’re asking, “How much income can this account reliably provide me every month for the rest of my life?”
Those are not the same question.
Imagine retiring with $750,000 in a 401(k). That’s certainly an accomplishment. But what does $750,000 mean in terms of a paycheck? Can you withdraw $30,000 a year? $40,000? $50,000? What happens if the market drops substantially during your first few years of retirement? What happens if you live to 95?
Suddenly, having a retirement account and having a retirement income plan begin to look like two very different things.
What If You Could Rebuild the Missing Pension Leg?
This is where annuities can play an important role in retirement income planning.
Depending upon the type of annuity and the guarantees selected, a portion of retirement assets can potentially be converted into a contractually guaranteed stream of income that cannot be outlived, subject to the claims-paying ability of the issuing insurance company.
In other words, instead of waiting for an employer to provide the pension, today’s retiree may be able to create a personal pension-like income stream.
Assets accumulated in plans such as 401(k)s, 403(b)s, governmental 457(b)s, traditional IRAs and certain other qualified retirement accounts may generally be eligible to move through a properly structured direct rollover or trustee-to-trustee transfer into an IRA annuity without creating an immediate taxable distribution.
The money remains tax-deferred, and income taxes generally become due as taxable amounts are distributed.
That can allow someone to take part of the money they spent 30 or 40 years accumulating and assign it a new job: Produce dependable retirement income.
You Don’t Necessarily Have to Put Your Entire Retirement Account Into an Annuity
Creating guaranteed income doesn’t necessarily mean annuitizing every dollar you’ve accumulated.
For many retirees, the better question is: How much guaranteed income do I need?
Start with essential monthly expenses. Then look at the reliable income already coming into the household: Social Security, any existing pension, rental income or other dependable sources.
If there’s a gap between dependable income and essential expenses, a properly designed annuity may potentially be used to help fill that gap.
The remaining assets can continue serving other purposes, including liquidity, growth, emergencies and legacy planning.
That begins to recreate the philosophy behind the original three-legged stool.
The Three Legs Didn’t Disappear. One Became Your Responsibility.
The old retirement model looked something like this:
Pension + Social Security + Personal Savings
For many of today’s retirees, it might instead look like:
Personal Guaranteed Income + Social Security + Investments/Savings
The objective isn’t to recreate your grandfather’s pension plan exactly. It’s to recreate something the pension provided: A paycheck you could count on.
Because ultimately, retirement isn’t about having the biggest account balance on the day you retire. It’s about converting the assets you’ve accumulated into the life you want those assets to support.
For previous generations, employers often helped solve that problem through pensions. For today’s generation, we increasingly have to solve it ourselves.
And understanding how to turn a portion of your retirement savings back into predictable lifetime income may be one of the most important decisions you make as you approach retirement.
Ready to Find Your Retirement Income Gap?
If you’re approaching retirement and wondering how much dependable income your 401(k), 403(b), 457 or IRA could potentially produce, Reservepoint Financial can help you evaluate the numbers.
We’ll look at your Social Security, existing income sources, retirement accounts and expected expenses to identify your retirement income gap — and determine whether creating your own pension-like income stream makes sense for your situation.
Schedule a complimentary retirement income review.
Educational material only. Annuity guarantees are backed by the claims-paying ability of the issuing insurance company. Tax treatment depends on individual circumstances; consult an appropriate tax professional regarding your situation.